

What if the number that feels most important in your finances is also the easiest to miscalculate? If you’re wondering how to calculate my net worth accurately, the challenge isn’t just adding up balances. It’s deciding what to include, finding consistent current values, and avoiding double-counting.
That can feel especially unclear in Singapore. Should you count CPF balances even though they aren’t readily available to spend? How should you value an HDB flat or private property, account for its mortgage, or treat joint and overseas assets? A reliable snapshot starts with clear categories and careful records, not a complicated spreadsheet. If you have assets or debts across Singapore, Indonesia, Malaysia, the Philippines or Thailand, consistent currency conversion and ownership records matter too.
This guide will help you total your assets and liabilities, estimate property values using relevant Singapore sources, and include CPF, insurance, investments and shared holdings appropriately. You’ll also learn what your net-worth figure can and can’t tell you, and how to use it as one practical input to wider financial planning. Keep investment records, including any relevant to i12 investments, within the same consistent review. The aim is a clearer starting point for your next financial decisions.
Key Takeaways
- Learn how to calculate my net worth accurately by recording assets and liabilities on one chosen date and subtracting what you owe from what you own.
- Use current statements and suitable valuation evidence to estimate property, CPF, investments and other assets without treating them all as cash you can spend.
- Check ownership shares, outstanding debts and valuation dates before adding figures. This helps catch missing items and common double-counting errors.
- Review investment records, including any relevant to i12 investments, as part of your wider financial picture.
- Use changes in net worth alongside liquidity and debt when planning next steps. The total alone doesn’t determine investment decisions or retirement outcomes.
What Net Worth Measures, and Why an Accurate Figure Matters
Your net worth is the value of what you own minus the amounts you owe, measured on a particular date. In formula form: total assets − total liabilities = net worth. The basic idea is straightforward, but the result is useful only when the figures cover the same person, ownership share, currency and valuation date. The Net worth overview also describes the measure in terms of assets and liabilities.
Keep net worth separate from income. Income is money received over time, such as salary or business income. Net worth is a balance-sheet snapshot: it shows your financial position at one moment, not how much you earn each month or how comfortably you can meet your next expense. Someone can have a high income and substantial debt, or a modest income and significant accumulated assets.
What counts as an asset or a liability?
Assets are things with financial value that you own or partly own. They may include cash, investments, property or other valuable possessions. Liabilities are outstanding amounts you’re responsible for repaying, such as a mortgage, personal loan or credit-card balance. For shared property or accounts, record only your ownership share. For shared debts, use a consistent approach that reflects the portion you’re responsible for. Don’t count the full amount in one place and a partial amount elsewhere.
Why a snapshot needs a date
Net worth is a dated balance-sheet snapshot of the assets you own and the liabilities you owe on a chosen day. Record that date beside each calculation. Bank balances and debts can change as transactions clear or repayments are made, while investment prices and property estimates may move. Mixing values from different dates can make the total look more precise than it is.
Accuracy doesn’t mean predicting the exact amount you could receive for every asset. It means making a reasonable estimate, using clear categories and applying the same method each time. For example, if your assets total S$750,000 and your liabilities total S$300,000 on the chosen date, your net worth is S$450,000. The calculation is useful only if the figures are complete and each amount is counted once.
To work out how to calculate my net worth accurately, treat the final figure as one planning input, not a verdict on your financial wellbeing. It doesn’t show how much cash is readily available, whether your income covers your spending, or what your future investment or retirement outcomes will be. Review investment holdings, including any you’re considering in connection with i12 investments, within the same consistent picture. The next step is to build that snapshot using clear records and valuation choices.
How to Calculate Net Worth Accurately in Singapore
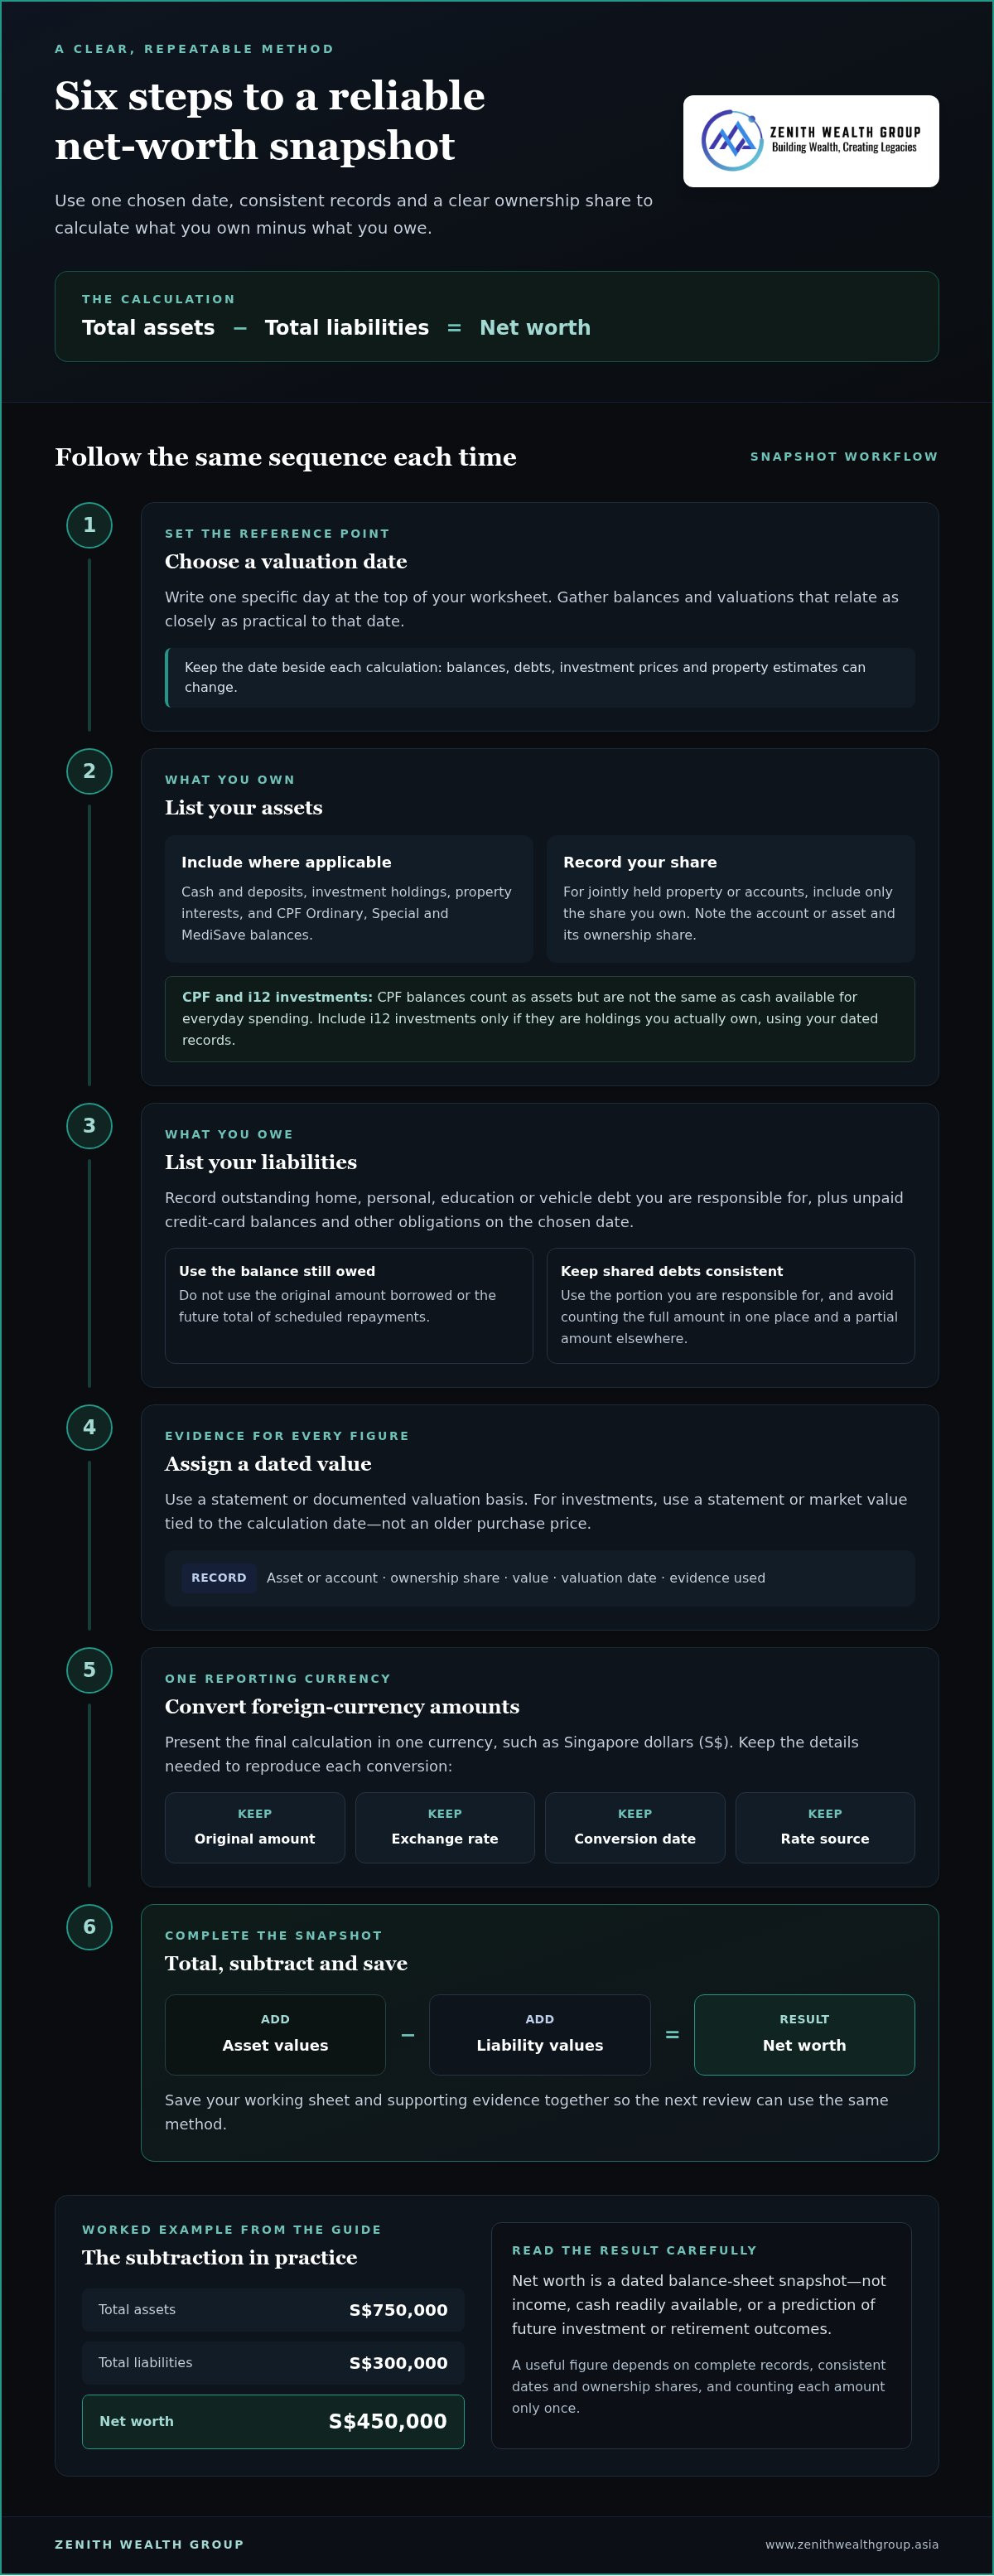
Use one repeatable method and keep the supporting records with your figures. The aim is to make a clear calculation you can review later, not to make every estimate look exact. To learn how to calculate my net worth accurately, work through the same sequence each time:
- Choose a valuation date. Use a specific day and note it at the top of your worksheet. Gather balances and valuations that relate as closely as practical to that date.
- List your assets. Include cash and deposit balances, investment holdings, property interests and CPF balances where applicable. Record only the share you own if an asset is jointly held.
- List your liabilities. Include outstanding home, personal, education or vehicle debt you’re responsible for, along with unpaid credit-card balances and other obligations on the chosen date.
- Assign a value to each item. Use a dated statement or a documented valuation basis. For investments, use a statement or market value tied to the calculation date rather than an older purchase price.
- Convert foreign-currency amounts. Present the final calculation in one currency, such as Singapore dollars (S$). Keep the original amount, exchange rate, conversion date and rate source beside each converted figure so you can reproduce it later.
- Total and subtract. Add the asset values, add the liability values, then subtract total liabilities from total assets. Save your working sheet and evidence together for the next review.
Which Singapore-relevant assets should you list?
Include CPF Ordinary, Special and MediSave account balances where applicable, using the displayed account information for your chosen date. These balances count as assets, but they aren’t the same as cash available for everyday spending. For funds and securities, keep the relevant account statement or documented market value. Include i12 investments only if they reflect holdings you actually own, and value them using your own dated records.
For each entry, note the account or asset, your ownership share, its value, the valuation date and the evidence used. This makes it easier to trace a number to its source instead of relying on memory. If you’re preparing a broader financial picture, these records can support a discussion with a financial planning consultant.
Which liabilities belong in the calculation?
Record the amount still outstanding on each debt, not the original amount borrowed or the future total of scheduled repayments. For a shared loan, apply a consistent approach to the portion you’re responsible for. Use account records to check the balance, and note any unpaid card purchases as liabilities at the valuation date.
Watch for overlap between transactions and balances. If a card purchase is already included in the card balance, don’t list it again as a separate debt. Likewise, don’t subtract a loan payment twice if it’s already reflected in the account balance you recorded. Consistent treatment across assets and liabilities keeps the result useful from one review to the next.
How to Value Property, CPF, Investments, and Other Complicated Items
Some assets have a clear balance on a statement. Others need an estimate, and an estimated value isn’t the same as money you can spend immediately. Record both the valuation basis and how accessible the asset is. This distinction makes how to calculate my net worth accurately more useful than simply producing a headline total.
| Item | Suggested valuation basis | Evidence source | Liquidity note |
|---|---|---|---|
| HDB or private property | Dated estimate of likely resale value | Recent comparable transactions on HDB or URA websites | Not cash readily available; sale takes a transaction |
| CPF balances | Displayed balances for the chosen date | Current CPF account information | Not freely available for everyday spending |
| Shares, funds, and other investments | Documented market value on or near the valuation date | Dated account statement or portfolio record | Value can change; access may involve selling or other steps |
| Insurance policy | Documented cash value, if applicable | Current policy statement | Coverage itself isn’t cash or an asset value |
How should you value property and joint assets?
Label a property figure as an estimate and write down its date and basis. For a practical resale estimate in Singapore, compare recent transactions for similar properties using HDB or URA sources. IRAS Annual Value is an estimate of gross annual rent used for property tax purposes, not a direct estimate of sale value. An HDB Request for Value is part of a buyer’s transaction process, so don’t treat it as a universal current-market valuation.
For jointly owned property, include only your share of the estimated value. Then deduct your corresponding share of the outstanding mortgage, using a consistent ownership approach. Use the current loan balance, not the original amount borrowed. This prevents the property and mortgage figures from describing different shares or dates.
How should CPF, investments, and foreign-currency holdings be treated?
Use current CPF account figures, including OA, SA and MediSave balances where applicable. Include them as assets, but don’t mistake inclusion in net worth for immediate access to the money. For investments, use a dated statement or documented market value. Include i12 investments only if they represent holdings you actually own, and use their recorded value rather than assuming a product or amount.
For assets or debts held in another currency, keep the original balance alongside the converted Singapore-dollar figure. Record the exchange-rate source and conversion date, then apply the same approach consistently to both foreign assets and foreign liabilities. This is particularly useful when your financial records span Singapore, Indonesia, Malaysia, the Philippines or Thailand.
Keep the supporting statement or valuation evidence beside each figure. If a value is uncertain, mark it as an estimate instead of adding false precision. For insurance, count only a documented cash value where one applies. Don’t add the amount of cover as though it were an asset.
A Practical Accuracy Check: Avoid Double-Counting and False Precision
Before accepting your total, audit the entries rather than relying on the final number to look plausible. A short checklist can reveal omissions and overlaps that are easy to miss when accounts, property and debts are recorded in separate places.
- Check current statements for every bank, investment and CPF account you intend to include.
- Look for outstanding mortgages, personal or other loans, unpaid card balances and shared debts.
- Confirm the ownership share recorded for each jointly held asset and liability.
- Check that each value relates to the same chosen date, or clearly label any estimate taken from another date.
- Keep a note of the evidence and method behind each figure, including currency conversions.
Next, reconcile your worksheet with the records. Compare each account entry with its statement balance for the valuation date, and check that each liability uses the outstanding balance rather than the amount originally borrowed. If an account statement covers a different date, note the difference instead of presenting it as a same-day figure. For estimates, such as a property value, record the basis and mark the result as an estimate. Don’t add extra decimal places to a value that is only approximate.
What errors make a net-worth calculation inaccurate?
A common property error is recording the full estimated value without the related mortgage liability. Record the asset and outstanding loan together, using a consistent ownership share. Another mistake is counting money twice as it moves: if cash leaves a bank account and is invested, include the resulting investment value and the bank’s remaining balance, not the original cash amount as well.
Credit-card spending can also be counted twice. If a purchase is already represented in the card balance, don’t list it again as a separate liability. Also distinguish insurance protection from an asset: a coverage amount is not cash value. Include a policy’s cash value only when one applies and you have documentation for it.
How often should you update the calculation?
Choose a review interval that fits your needs and records, then use it consistently. At each review, keep the same asset and liability categories, valuation approach and currency method. If you change a method, make a note so you can distinguish a real financial change from a different way of measuring.
Consistent methods make changes in net worth easier to interpret over time. That’s the practical value of a repeatable process: you can trace a change to updated balances, valuations or debts instead of wondering whether the calculation itself changed. To connect your snapshot to wider financial planning, you can read more about financial planning.
Use Your Net-Worth Snapshot to Guide Your Next Financial Conversation
A net-worth figure becomes more useful when you look beyond the total. Compare it with your previous snapshot, then check which categories changed: cash, investments, property, CPF balances or debts. Ask what may have contributed. Saving more, repaying a loan, taking on new borrowing or market movements can all affect the picture in different ways.
Review liquidity alongside the total. A large share of your wealth may be held in property, CPF or investments rather than cash available for near-term expenses. Look at outstanding debts, too. A rising net worth doesn’t automatically mean your monthly cash flow is comfortable, and a falling figure doesn’t, by itself, tell you what action to take.
What does a rising, falling, or negative figure tell you?
Start with the reasons behind the change, not a judgment about whether the number is good or bad. If investment values moved, separate that change from new contributions or withdrawals. If debt increased, consider whether it came with an asset or another financial commitment. A negative figure is a prompt to understand the balance of assets and obligations, not a prediction of what your future will be. No single net-worth figure guarantees financial security or a particular retirement outcome.
For a clearer comparison, place the current and previous snapshots side by side. Note any changes in valuation methods or ownership shares, since those can affect the total without reflecting a change in your underlying finances. This context helps you decide what questions matter next.
When can a financial consultant help interpret the picture?
A financial consultant can help connect your assets, liabilities, cash-flow needs and priorities to a wider financial plan. Bring your dated snapshots and the questions they raise. You might want to discuss how your current position relates to retirement planning, wealth protection or another goal. If you are deciding what type of professional support aligns with your goals, guides from Her Financial Planning explain how wealth management and financial planning address different aspects of your finances. If you hold investments, include them in the picture as part of your actual investment holdings, without assuming that a single figure determines whether they suit your needs.
The calculation is a starting point, not a recommendation to buy, sell or change an investment. Decisions should take account of your circumstances, goals and time horizon, as well as the limits of what a net-worth snapshot can show. If you’re unsure how to calculate my net worth accurately over time or how to use the result in planning, a conversation can help you organize the questions before deciding on next steps.
Zenith Wealth offers a free 30-minute discovery session to match you with a consultant. Learn about the free 30-minute discovery session.
Turn Your Financial Snapshot Into a Clear Next Step
A clear financial picture can help you ask better questions about what matters next. Choose a priority, such as preparing for retirement, protecting your family or planning how to pass on wealth. Then consider what information you still need to make decisions with confidence. Knowing how to calculate my net worth accurately is a useful starting point, but the next step is connecting that information to your own goals and circumstances.
A financial consultant can help connect your assets, liabilities and priorities to a wider plan. At Zenith Wealth Group, authorized Financial Consultants representing finexis advisory Pte Ltd [Reg No 200408660G] can help you explore your financial planning questions. You can find further information about financial planning with Zenith Wealth Group.
You don’t need to have every answer before you begin. Bring the questions that matter most to you, and use the conversation to clarify a practical way forward. A thoughtful next step can make your financial picture feel more manageable.
Frequently Asked Questions
What is the formula for calculating net worth?
Subtract your total liabilities from your total assets: assets − liabilities = net worth. For example, if your recorded assets are S$500,000 and your debts total S$180,000, the result is S$320,000. Use this as a calculation example, not a target. To understand how to calculate my net worth accurately, make sure every figure refers to the same person or ownership share and is recorded consistently.
Should I include my CPF balances when calculating my net worth?
Yes, include your CPF balances as assets using the figures shown in your current account information. Their inclusion reflects their value in your overall financial position, not that they’re available as everyday spending money. For a useful comparison later, save the date of the CPF figures and the account information you used. If you review your finances with a planner, keep CPF separate from cash savings when discussing near-term needs.
How do I include my home and mortgage in a net-worth calculation?
Record your share of the home’s estimated value and account for the corresponding outstanding mortgage liability. For jointly owned property, use a consistent share for both entries. This gives a clearer view of your property-related position than listing a home value alone. Keep the property estimate and loan balance as separate lines in your working, so you can see whether a change comes from the estimate or from mortgage repayments.
Do I include insurance coverage or only its cash value?
Don’t count the coverage amount as an asset. It describes protection under the policy, not money you own as a balance. If your policy has a cash value and you can document that value in a current statement, you may include that amount instead. Keep the policy record with your calculation and label the figure clearly, so it isn’t mistaken for a payout you can access simply because the coverage amount is stated.
Should I include investments that I cannot easily sell?
Include an investment you own if you can support its value with a reasonable record, even if it may take time or require steps to sell. Mark it as less liquid rather than treating its estimated value as spending cash. This distinction can matter in a planning conversation: holdings such as i12 investments should be assessed from your actual records, without assuming a value or that they can be sold immediately.
What does it mean if my net worth is negative?
A negative result means the liabilities recorded exceed the assets recorded on that date. It doesn’t, on its own, describe your income, monthly cash flow or ability to meet payments. Review which debts make up the total, whether the figures are current, and how the balance changes over time. The useful next question is what is driving the result and which financial priorities need attention, not whether the number defines your future.
How often should I calculate my net worth?
Choose a review schedule you can maintain, such as aligning it with a regular personal finance review, and use the same approach each time. A predictable routine makes it easier to spot changes without reacting to every market movement. Keep prior versions of your worksheet, including dates and notes about estimates or method changes. If your circumstances shift substantially, you can also make an additional snapshot to inform a planning discussion.


