
Why does that extra RM1,200 in your monthly bank statement seem to vanish before you even have a chance to celebrate? It is a frustrating reality for many professionals in cities like KL and Penang who want to know how to avoid lifestyle inflation with a pay raise in Malaysia. You work hard for a promotion, but somehow, your savings balance stays stubbornly flat. The social pressure to upgrade your car or move to a trendier condo is intense. You might feel like you are running faster just to stay in the same place. We understand that tension between wanting to enjoy your success today and needing to feel secure about your future.
Turning a salary increase into wealth requires a deliberate plan. In this guide, we will show you how to transform your next raise into a long term wealth catalyst without sacrificing your current happiness. We will introduce the i12 investments framework and explain why a quick check in with a financial planner can make all the difference. You will learn how to balance your EPF contributions with private investments to ensure you are building a legacy that lasts. It is time to make your income work as hard as you do. Let us start building that security together.
Key Takeaways
- Master the essential steps of how to avoid lifestyle inflation with a pay raise in Malaysia by identifying your actual net increase after taxes and EPF.
- Uncover the psychological traps that lead to invisible spending and learn how to pause before making major lifestyle upgrades.
- Discover how to use the i12 investments framework to turn your monthly surplus into a powerful engine for wealth protection and growth.
- Understand why a financial planner offers a more robust defense against inflation than a standard budgeting app.
- Create a bespoke roadmap that balances immediate rewards with long term goals like retirement planning and legacy building.
Understanding Lifestyle Inflation in the Malaysian Context
Lifestyle inflation happens when your "wants" suddenly become "needs" the moment your salary increases. It is a subtle process. Economists often call this lifestyle creep. You might start choosing slightly more expensive coffee or upgrading to a premium gym membership. Individually, these choices seem small. Collectively, they consume your entire raise. Learning how to avoid lifestyle inflation with a pay raise in Malaysia is about recognizing these patterns before they lock you into a cycle of working just to pay for your new expenses. You deserve to enjoy your hard work, but you shouldn't let it compromise your future security.
In urban hubs like KL or Penang, the "Keeping up with the Tans" effect is real. Social pressure to drive a certain car or live in a specific postcode can be overwhelming. As we look toward 2026, global economic volatility makes it even more vital to secure your surplus. Inflation in major Malaysian cities continues to fluctuate, impacting everything from groceries to utilities. If you don't capture your pay raise now, it will simply dissolve into the rising cost of living. A proactive approach allows you to build a buffer against these external shifts while others are struggling to maintain their new, more expensive habits.
The Difference Between Standard of Living and Quality of Life
Your standard of living is defined by what you buy. This includes your car, your home, and your gadgets. Quality of life is different. It is about your health, your free time, and your freedom from financial stress. Many people increase their standard of living by taking on more debt. This often decreases their quality of life because they end up stressed by high monthly commitments. True wealth is having the freedom to choose how you spend your time. By consulting a financial planner, you can ensure your raise boosts your happiness without weighing you down with unnecessary liabilities.
Common 'Raise Traps' in Malaysia
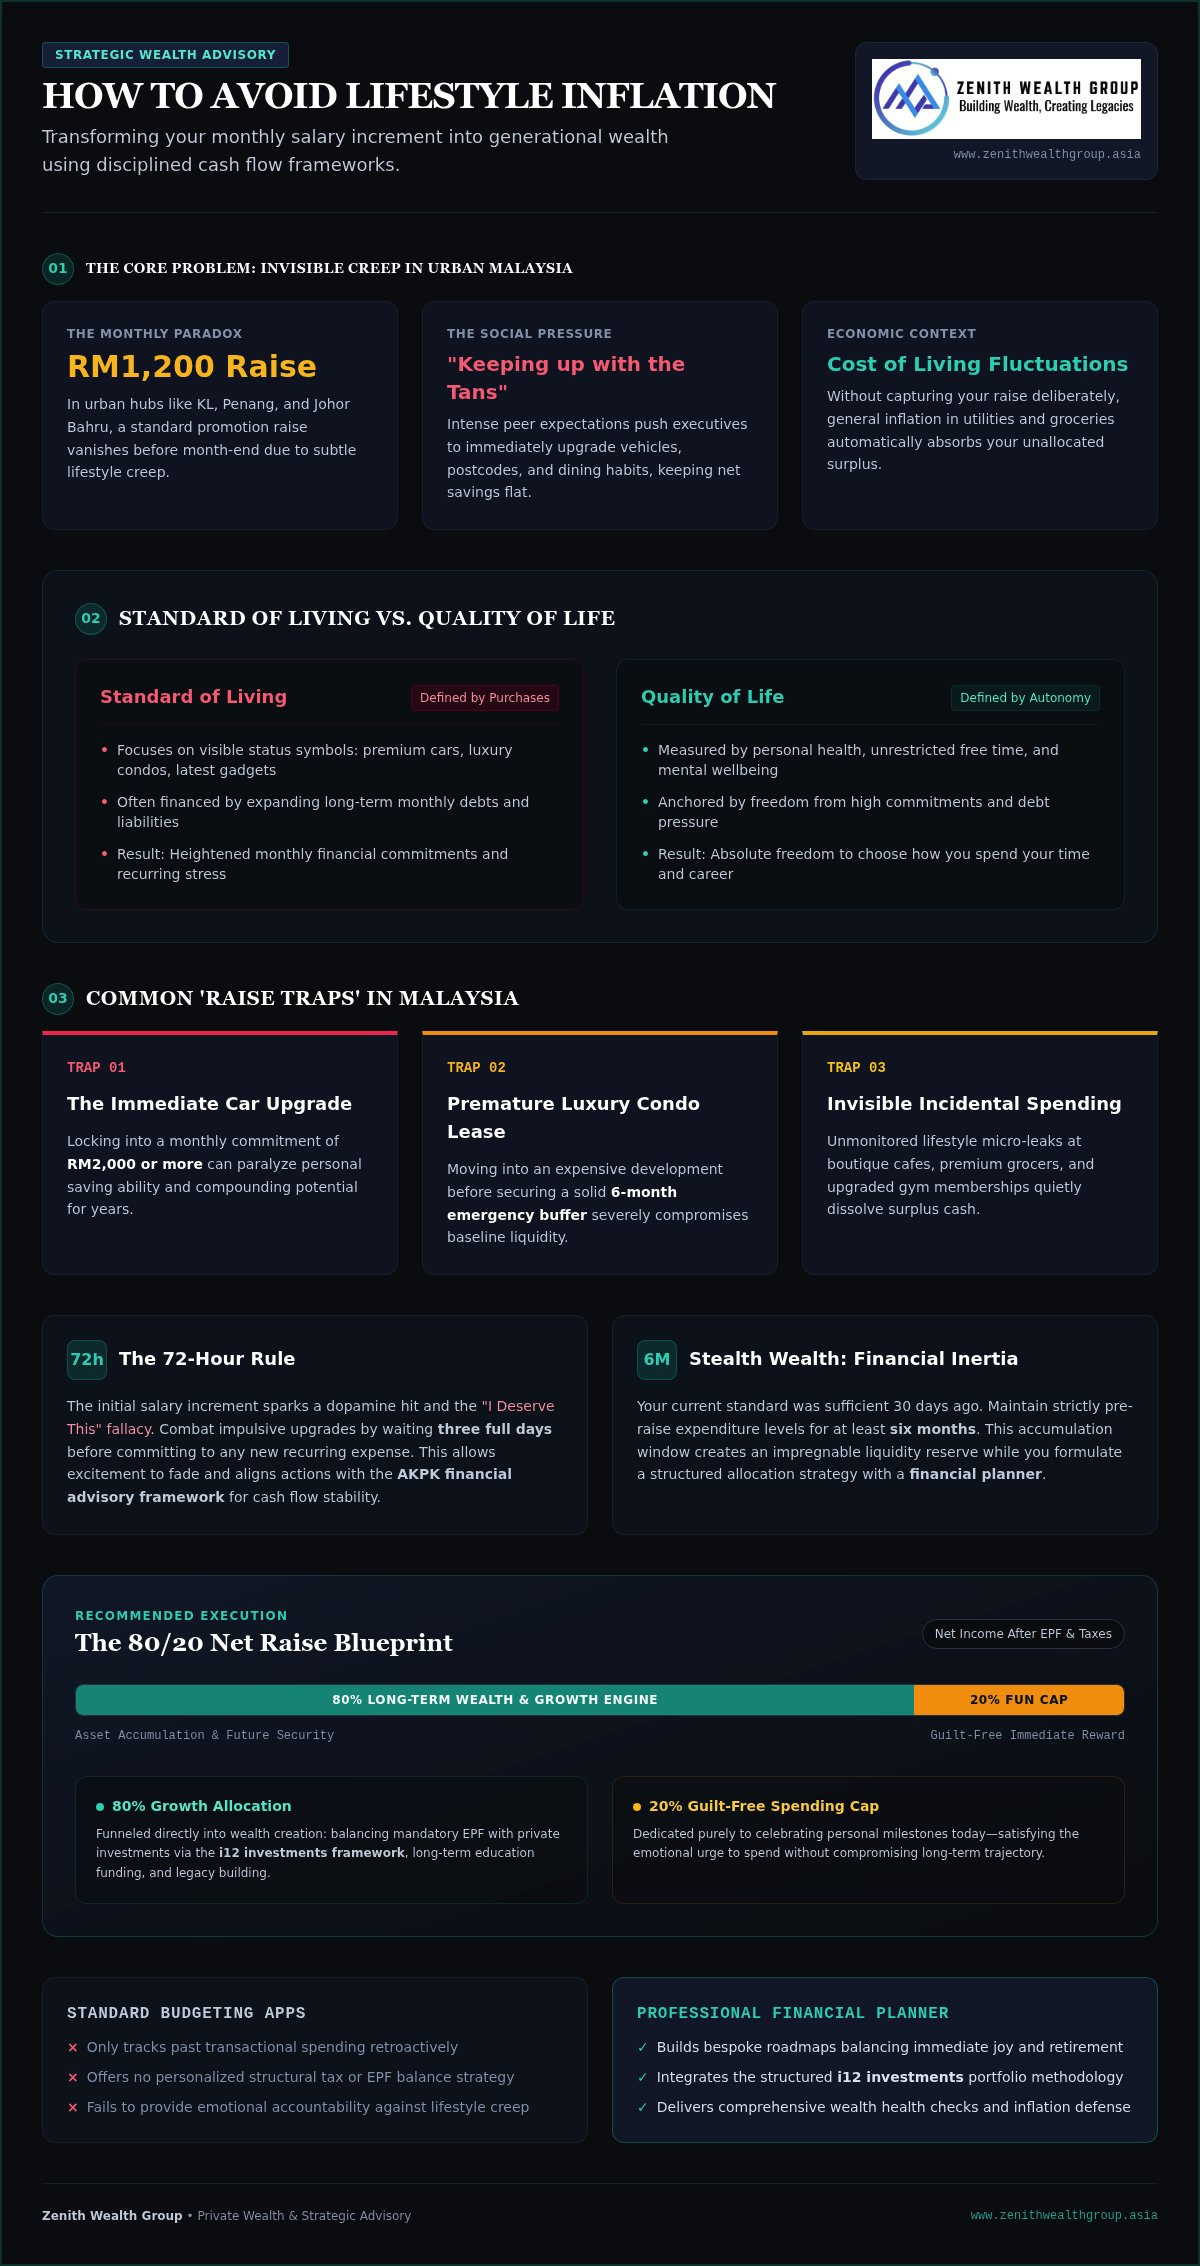
The most dangerous trap is the immediate car upgrade. Committing to a monthly payment of RM2,000 or more can paralyze your ability to save for years. Other common traps include moving to a luxury condo before you have a six month emergency fund or increasing your "incidental" spending at premium grocers and boutique cafes. These leaks are often invisible until you check your bank statement at the end of the month. Instead of letting your raise disappear, consider a wealth health check. Incorporating frameworks like i12 investments can help you redirect that extra income into assets that grow over time, securing your legacy while you still enjoy the present.
The Psychology of the Raise: Why We Want to Spend
Receiving news of a salary increase triggers an immediate emotional rush. Your brain treats the extra income as a reward for past sacrifices; this is often where the "I Deserve This" fallacy takes root. You might feel that because you worked late nights or hit difficult KPIs, you have earned the right to spend recklessly. However, understanding how to avoid lifestyle inflation with a pay raise in Malaysia starts with recognizing that your hard work deserves a more permanent reward than a fleeting purchase. Wealth isn't built by what you spend, but by what you keep.
The first month of a raise often feels like "free money" because your brain hasn't yet adjusted to the new baseline. This dopamine hit can cloud your judgment, making a larger car loan or a luxury holiday seem perfectly reasonable. In professional circles in Kuala Lumpur or Johor Bahru, social proof adds another layer of pressure. You might feel the need to look the part of a successful executive. To combat this, implement the 72-hour rule. Before committing to any new recurring expense, wait three full days. This buffer allows the initial excitement to fade, giving you the clarity to align your spending with the AKPK financial advisory framework for sustainable cash flow management.
Overcoming the 'Reward' Mindset
Shift your perspective on what a reward actually looks like. Instead of a new designer watch, view your raise as a ticket to a week of early retirement or a fully funded future for your children. You can satisfy the urge to celebrate by setting a "Fun Budget" cap. Allocating just 20% of your net raise to guilt free spending allows you to enjoy your success while the remaining 80% is funneled into growth. This discipline is essential when planning for major milestones like Education Funding, ensuring your family's needs are met without stress.
The Power of Financial Inertia
Your current lifestyle was sufficient just 30 days ago. There is immense psychological power in financial inertia; the act of staying at your current spending level even as your income climbs. Try to maintain your "pre-raise" expenses for at least six months. This period of "stealth wealth" allows you to build a significant cash buffer while you work with a financial planner to integrate the i12 investments framework into your portfolio. By the time you decide to upgrade any part of your life, you will be doing so from a position of absolute security. If you are ready to see how your new income can work for your future, it might be time to speak with a financial planner for a personalized strategy.
A 5-Step How-To Guide for Your New Salary
Understanding the theory of wealth is one thing; applying it to your bank account is another. To master how to avoid lifestyle inflation with a pay raise in Malaysia, you need a repeatable system that removes emotion from the equation. Your next salary bump is an opportunity to accelerate your journey toward financial freedom. By following a structured approach, you can ensure that your hard earned success results in a stronger balance sheet rather than just a more expensive lifestyle. Let's break down the five essential steps to manage your new income effectively.
Step 1 & 2: Real Numbers and Safety Nets
Start by calculating your actual net increase. Do not rely on the gross figure mentioned in your performance review. You must factor in the 2026 Malaysian tax brackets and your EPF contributions to understand the real amount hitting your account each month. If your raise is S$1,000, your actual take-home pay might be significantly less. Once you have a realistic figure, use it to fortify your foundation. Prioritize clearing any high interest debt, such as credit card balances or personal loans. Experts suggest that avoiding lifestyle creep requires a "defense first" mindset. Aim to expand your emergency fund to cover 6 to 12 months of expenses, accounting for the slight increase in costs that inflation may bring by 2026.
Step 3 & 4: Automation and Protection
The most effective way to save is to automate the delta. Set up a standing instruction to move your extra income into a separate investment account on payday. If the money is gone before you can spend it, you won't feel the urge to upgrade your daily habits. This is also the perfect time to review your Wealth Protection coverage. A higher income often supports a higher standard of living for your family, which means your insurance and Legacy Planning must be updated to reflect your new value. Ensure your loved ones are protected at your new earning level so that your wealth remains secure regardless of what the future holds.
Finally, consult a financial planner to adjust your long term roadmap. Your goals may have evolved now that you have more capital to deploy. A professional can help you integrate the i12 investments framework into your portfolio, ensuring your assets are allocated for maximum efficiency. If you are ready to turn your raise into a wealth catalyst, connect with a financial planner today for a bespoke wealth health check. Taking this step now ensures your raise builds a legacy rather than just funding temporary upgrades.
Strategic Allocation: The i12 Investments Framework
A pay raise is more than just extra cash; it's a strategic tool. Once you've fortified your foundation, the next challenge is deciding where to put that capital to work. This is how to avoid lifestyle inflation with a pay raise in Malaysia effectively. Instead of letting the money sit in a low interest savings account, you should adopt a framework that prioritizes growth and resilience. The i12 investments approach serves as the gold standard for this transition. It ensures that your surplus doesn't just sit idle but actively builds your future legacy.
Relying solely on your mandatory EPF contributions is a common mistake. While the standard 11% employee contribution is a great start, it's rarely enough to sustain a comfortable early retirement in 2026. You need to look beyond these local safety nets. Diversifying into global assets or private managed funds allows you to capture growth outside the domestic market. This proactive allocation is what separates those who simply earn more from those who actually become wealthy. Whether your raise is S$500 or S$2,000, every dollar needs a specific job description.
What is the i12 Investments Approach?
The i12 investments framework focuses on systematic, evidence based wealth accumulation. It removes the emotional urge to "time the market" with your new income. When you receive a raise, the temptation to wait for a "better time" to invest can lead to missed opportunities. This structured approach ensures you stay consistent regardless of market noise. It aligns perfectly with your broader Investment Management goals. By automating your contributions into this framework, you transform your salary into a productive asset that compounds over time.
Optimising Local Malaysian Vehicles
Deciding between voluntary EPF contributions and private managed funds requires careful analysis. Your choice should depend on your liquidity needs and tax position. Many professionals in 2026 are looking toward Shariah compliant or global assets to hedge against local currency volatility. The i12 investments mindset encourages you to look at the total picture of your wealth rather than just isolated accounts. i12 investments provides a structured path for salary surpluses. Whether you are targeting aggressive growth or wealth protection, having a clear roadmap is essential. If you're ready to see how this framework fits your specific situation, book a consultation with a financial planner to start your bespoke wealth health check.
Why a Financial Planner is Your Best Defense Against Inflation
A budget app can tell you where your money went, but it cannot tell you where it should go. When you are looking for how to avoid lifestyle inflation with a pay raise in Malaysia, you need more than a digital spreadsheet. You need a partner who understands the nuances of the 2026 economic landscape. A professional financial consultant provides a bespoke roadmap that accounts for specific Malaysian inflation trends in cities like KL and Penang. They help you look past the immediate gratification of a higher salary to see the long term impact on your wealth. This personal touch ensures your plan is as unique as your career path.
Apps often lack the human element of accountability. It's easy to ignore a notification on your phone when you're standing in a car showroom. It's much harder to ignore a strategic plan you've built with a professional. By integrating the i12 investments framework, a financial planner ensures that your salary surplus is working toward your most important goals. They provide the objective perspective needed to distinguish between a genuine quality of life improvement and a standard of living trap that will drain your resources over time. This guidance is vital for maintaining your trajectory toward financial freedom.
Accountability and Expertise
DIY financial planning often fails because emotions are powerful drivers of behavior. When you receive a raise of S$1,200 or more, the urge to spend is biological. A financial consultant identifies "leaks" in your cash flow that you might overlook. They ensure your new income is aligned with critical Retirement Planning milestones. This level of expertise transforms a simple pay increase into a wealth building engine. You aren't just saving money; you are buying back your future time. Having a professional to answer to makes all the difference in staying disciplined.
Taking Action Today
Don't wait for your next promotion to start your planning journey. The decisions you make in the first month of a raise have a massive compound effect. If you capture that extra S$1,000 now and apply the i12 investments strategy, you're setting yourself up for decades of security. If you wait six months, you've likely already inflated your lifestyle to match your new income. The window of opportunity is narrow, but the rewards are significant. You've worked hard for this raise. Now, make sure it works hard for you. Ready to make your raise count? Connect with a Zenith financial consultant today to schedule your wealth health check. Let's build something that lasts.
Build a Wealth Catalyst That Lasts
Your next salary increase represents a unique opportunity to change your financial trajectory. Throughout this guide, we have mapped out how to avoid lifestyle inflation with a pay raise in Malaysia by understanding the psychological triggers of spending and implementing a rigorous 5-step plan. By shifting your focus from a higher standard of living to a higher quality of life, you protect your future self from the invisible drain of lifestyle creep. Integrating the i12 investments framework ensures your surplus is allocated with precision and purpose.
At Zenith Wealth, we specialize in helping professionals navigate these transitions with confidence. Our team provides tailored roadmaps and expert advisory as authorized representatives of finexis advisory Pte Ltd. We don't just offer generic advice; we provide the accountability you need to stay the course toward early retirement and legacy building. Secure your financial future-book a consultation with our experts to start your bespoke wealth health check today. You have earned this success. Now, let's make it permanent.
Frequently Asked Questions
What is the 50/30/20 rule, and should I change it after a raise?
The 50/30/20 rule allocates 50% of income to needs, 30% to wants, and 20% to savings. When your income grows, you should ideally tighten these ratios to accelerate wealth building. Instead of keeping "wants" at 30%, consider capping them at a lower percentage of the new surplus. This is a primary strategy for how to avoid lifestyle inflation with a pay raise in Malaysia. Focus on funneling the majority of the raise into your savings bucket.
How much of my pay raise should I actually save in Malaysia?
A common benchmark is to save at least 70% to 80% of your net raise. Since your current lifestyle was already covered by your previous salary, most of the new income is extra. Saving a high percentage ensures you don't grow accustomed to expensive habits. A financial planner can help you determine the exact figure, such as S$800 out of a S$1,000 raise, based on your current debt levels and long term goals.
Is it better to pay off my car loan or invest the extra money from my raise?
The decision depends on the interest rate of your loan versus your expected investment returns. If your car loan interest is high, paying it off provides a guaranteed return. However, if the rate is low, investing the surplus into the i12 investments framework may yield better long term growth. A financial consultant can conduct a wealth health check to see which path strengthens your net worth most effectively in the current economy.
Should I increase my EPF contributions if I get a significant salary bump?
Increasing your EPF contributions is a safe way to automate savings, but it shouldn't be your only move. While the mandatory contribution is a foundation, you should also explore private investment management for better liquidity and diversification. Using the i12 investments approach alongside EPF allows you to capture global market growth. This balanced strategy is essential for those who want to reach financial independence earlier than the standard retirement age.
How often should I meet with a financial planner to review my salary growth?
You should meet with your financial planner at least once a year or whenever you receive a significant promotion. A pay raise is the perfect time for a wealth health check to ensure your roadmap is still accurate. These sessions provide the accountability needed to stay disciplined. Your consultant will help you adjust your strategy to account for current inflation trends and any new financial goals you have developed since your last review.
Can i12 investments help me retire earlier in Malaysia?
Yes, the i12 investments framework is designed for systematic wealth accumulation that outpaces standard savings accounts. By focusing on evidence based strategies rather than market timing, you can build a more robust portfolio. This approach helps you maximize the impact of every salary increase. When you combine this framework with professional guidance from a financial consultant, you create a clear path toward retiring years ahead of your peers in the region.
What are the first three things I should do the day I see my higher salary?
First, calculate your actual net take home pay after taxes and EPF. Second, set up an automated transfer to move at least 70% of the raise into an investment account. Third, book a session with a financial planner to update your long term strategy. Taking these actions immediately is the most effective way to understand how to avoid lifestyle inflation with a pay raise in Malaysia before the money is spent on temporary wants.
How do I handle pressure from friends or family to spend my new income?
Practice "stealth wealth" by keeping the exact details of your raise private. If you feel social pressure to upgrade your car or lifestyle after a S$1,000 raise, remind yourself of your long term goals. You don't need to look successful to be successful. Focus on building a legacy rather than seeking temporary approval. A financial consultant can help you stay grounded by showing you the tangible progress you are making toward true security.


