
Hiring a professional doesn't mean your wealth grows on autopilot. Many investors in Singapore assume that once they've engaged help, the heavy lifting is over; yet, they still find themselves staring at a stagnating portfolio. It's a common frustration. You see a sea of local investment options but feel a disconnect between the advice you receive and the actual results in your bank account. Understanding the common investment mistakes to avoid when working with a financial advisor in Singapore is the first step toward reclaiming your financial momentum.
We know you want more than just a list of stocks. You're looking for a high-performing, diversified portfolio and a transparent relationship with your financial consultant. You deserve peace of mind regarding your retirement roadmaps and education funding. This guide will show you how to transform a passive hand-off into a proactive partnership. We'll explore how to align your goals with the i12 investments framework to ensure every dollar works harder for you. From decoding complex fee structures to mastering the strategic errors that drain wealth, here is how you can secure your future in the 2026 market.
Key Takeaways
- Learn why viewing your financial consultant as a 'set and forget' service is a myth that often leads to lower realized returns.
- Identify the common investment mistakes to avoid when working with a financial advisor in Singapore, specifically the risks of withholding details about your CPF, SRS, and debt.
- Discover how to replace performance chasing with the disciplined rigor of the i12 investments framework for more consistent growth.
- Understand the high cost of analysis paralysis and why failing to implement your strategy is often more expensive than market volatility.
- Find out how a human-centric partnership with a financial planner provides the clarity needed for successful retirement and legacy planning.
The Delegation Myth: Why Hiring a Financial Consultant Isn't 'Set and Forget'
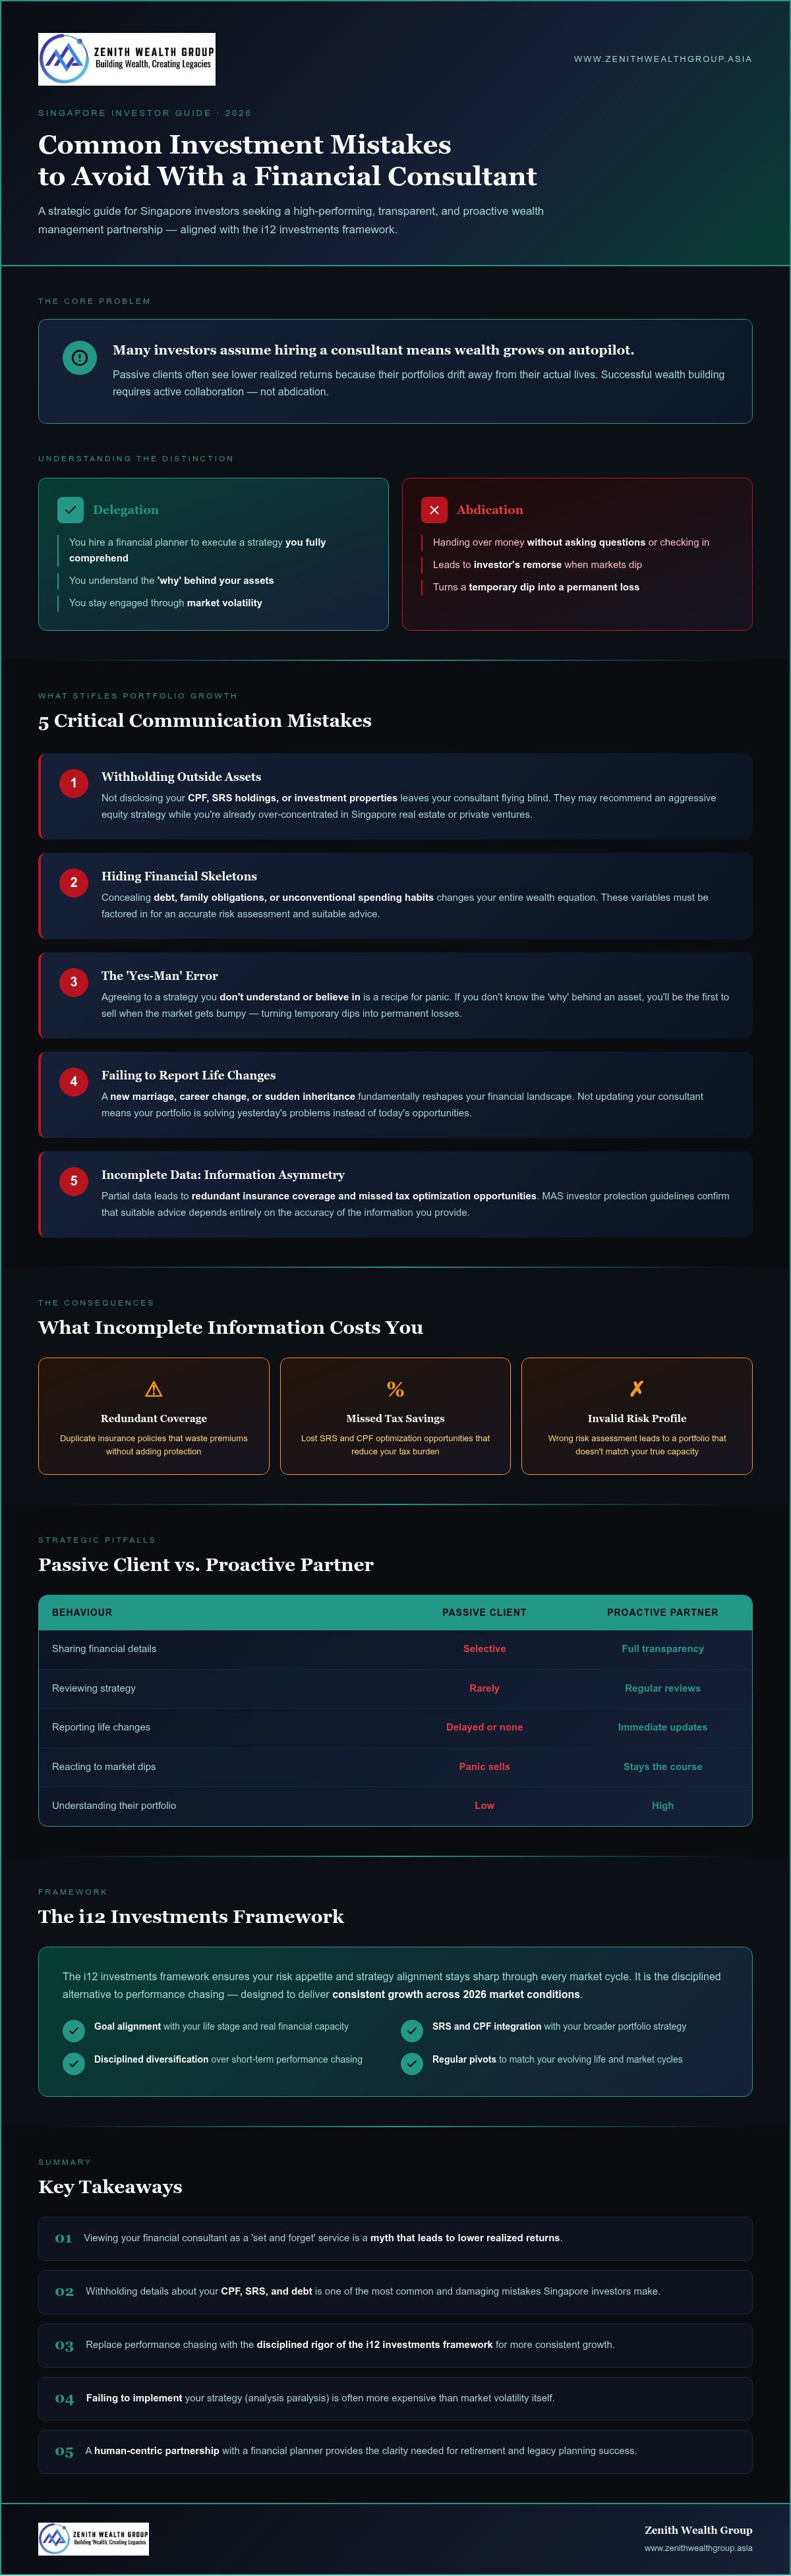
Hiring a professional is a smart move. However, believing that an expert's presence removes your personal responsibility is a dangerous trap. This is the 'Delegation Myth'. It's the false belief that wealth management is a one-way street where you drop off your capital and wait for a miracle. The truth is, passive clients often see lower realized returns because their portfolios drift away from their actual lives. One of the common investment mistakes to avoid when working with a financial advisor in Singapore is failing to participate in the process. Successful wealth building requires active collaboration. A proactive partnership is a dynamic relationship where the client provides the life vision and the consultant provides the technical execution.
The Difference Between Delegation and Abdication
Understanding this distinction is vital. Delegation means you hire a financial planner to execute a strategy you fully comprehend. You understand the 'why' behind your assets. Abdication is different. It's handing over your money without asking questions or checking in. When market volatility hits, abdication leads to investor's remorse. You panic because you don't understand the underlying investment management principles protecting your wealth. This lack of understanding is among the common investment mistakes to avoid when working with a financial advisor in Singapore, as it often leads to selling at the wrong time; it turns a temporary dip into a permanent loss.
Setting the Foundation for 2026 Wealth Goals
Your financial consultant needs more than just your bank balance. They need to know your life stage. Are you a young parent planning for education funding? Perhaps you're a pre-retiree focusing on retirement planning. Your risk appetite must align with your actual financial capacity. We use the i12 investments framework to ensure this alignment stays sharp through every market cycle. Regular reviews are not just formalities. They are the moments we pivot your strategy to match your evolving life. If you're ready to move from a 'paper plan' to a living strategy, you can reach out to our team to start that conversation.
5 Critical Communication Mistakes That Stifle Portfolio Growth
Wealth management is a two-way street. While your consultant brings the technical expertise, you bring the context. One of the common investment mistakes to avoid when working with a financial advisor in Singapore is treating your financial planner like a distant service provider rather than a partner. If you withhold information about "outside" assets like your CPF, SRS holdings, or investment properties, your consultant is essentially flying blind. They might recommend an aggressive equity strategy, unaware that you're already heavily over-concentrated in Singapore real estate or private business ventures.
Don't hide your financial skeletons. Debt, family obligations, or even unconventional spending habits are variables that change your wealth equation. Similarly, avoid the 'Yes-Man' error. Agreeing to a strategy you don't actually understand or like is a recipe for panic. If you don't believe in the 'why' behind an asset, you'll be the first to sell when the market gets bumpy. This lack of honest communication is a major hurdle to long-term success. Life moves fast, and failing to report major shifts like a new marriage, a career change, or a sudden inheritance means your portfolio is solving yesterday's problems instead of today's opportunities.
The Danger of Incomplete Financial Data
When you provide partial data, you create information asymmetry. This often leads to redundant insurance coverage or missed tax optimization opportunities. Transparency is the absolute key to Mastering the SRS Account and ensuring your voluntary contributions work in tandem with your broader portfolio. Without a full view, it's impossible to apply the i12 investments framework effectively. The investor protection guidelines in Singapore highlight that suitable advice depends entirely on the accuracy of the information you provide. Incomplete data is one of the most common investment mistakes to avoid when working with a financial advisor in Singapore because it invalidates the professional's risk assessment.
How to Give Honest Feedback to Your Financial Planner
Establish a 'no-jargon' zone from your very first meeting. If a recommendation sounds like alphabet soup, stop the conversation and ask for a plain-English explanation. Your financial planner is there to guide you, not to confuse you. If a specific investment feels misaligned with your personal values, speak up. A high-quality consultant welcomes healthy skepticism because it shows you're taking ownership of your future. If you feel like your current strategy is missing the mark, it might be time to connect with a consultant who prioritizes human connection alongside professional rigor.
Strategic Pitfalls: Avoiding Short-Termism and Lack of Diversification
Many investors fall into the trap of 'performance chasing'. They look at last year's top-performing funds and assume the trend will continue indefinitely. This is a recipe for failure. It's one of the common investment mistakes to avoid when working with a financial advisor in Singapore because it ignores the natural rotation of market cycles. Another major pitfall is the 'Singapore Bias'. It's tempting to over-invest in familiar local REITs or the big three banks. While these offer stability and dividends, relying on them exclusively limits your exposure to global growth sectors like AI, biotechnology, or emerging markets. In a 2026 context, the i12 investments framework provides a necessary counterweight by balancing regional stability with high-conviction global reward.
Integrating i12 Investments into Your Strategy
The core principles of i12 investments focus on capturing long-term wealth through structural trends rather than short-term spikes. This disciplined framework prevents emotional 'market timing' errors, which often plague retail investors. You won't find yourself jumping in at the peak or selling at the bottom because the strategy is data-driven and objective. This approach is particularly effective for Retirement Planning in Singapore, where consistency and compounding matter more than speculative wins. By sticking to a proven methodology, your financial planner can help you ignore the noise of the daily news cycle and focus on your specific milestones.
The Hidden Cost of Under-Diversification
Going 'all-in' on a single sector is a common error. Whether it is tech stocks or Singapore property, over-concentration leaves you vulnerable to specific regulatory or economic shifts. True wealth management requires balancing wealth protection with growth-oriented investment management. Global assets play a vital role here. They act as a hedge against local inflation and currency fluctuations. If the Singapore dollar shifts or the local property market cools, your global holdings provide a safety net. A well-diversified portfolio ensures that one bad sector doesn't derail your entire future. If you want to see how your current holdings stack up against global benchmarks, you can reach out to our team for a professional review of your current strategy.
The Implementation Trap: Why a Plan Without Action is Your Costliest Error
Planning is only half the battle. Analysis paralysis is a wealth killer that often disguises itself as "due diligence." Many investors spend months waiting for the perfect market entry point, only to miss out on the compounding growth that happens while they sit on the sidelines. This delay is expensive. A "paper plan" is just a wish list until you sign the documents and move the capital. One of the common investment mistakes to avoid when working with a financial advisor in Singapore is treating the strategy session as the finish line. Your financial consultant isn't just a strategist; they are your implementation officer. They help you bridge the gap between intent and action.
Don't ignore the "boring" administrative bits. Failing to update beneficiary nominations or draft a legal will can undo years of disciplined saving. If your wealth protection strategy isn't officially "in force" because of a missing signature or a pending medical check, your family remains at risk. Your financial planner can help automate these processes, ensuring that your i12 investments framework is actually working in the background while you focus on your career and family. Execution is what separates successful investors from those who simply have good ideas.
Overcoming Execution Friction
Removing friction is the key to progress. Start by setting a hard deadline. Give yourself exactly seven days after your consultation to review and sign all implementation documents. Next, automate your monthly contributions. Removing the "decision burden" ensures you stay consistent regardless of market headlines. Finally, schedule a 30-day follow-up with your financial consultant. This meeting isn't for a new strategy; it's a simple checklist to ensure every account is active and every nomination is filed correctly. Small steps today prevent massive gaps in your future portfolio.
The Role of Legacy and Estate Planning
An investment plan is incomplete without robust Legacy Planning. Common mistakes in beneficiary nominations often lead to legal delays that freeze assets for months. This is particularly critical in the Singaporean context, where specific probate laws apply. Ensure your wealth protection strategy is fully integrated with your estate plan. If your assets aren't structured to pass seamlessly to your heirs, you haven't finished the job. If you're unsure if your current plan is actually "in force," you should reach out to a financial planner to conduct an implementation audit today.
Building a Prosperous Partnership with Zenith Wealth
Zenith Wealth doesn't believe in the distant, institutional model of finance. We act as your Modern Professional Guide. Our focus is on building a partnership that values your human story as much as your balance sheet. By combining human connection with the technical rigor of i12 investments, we help you side-step the common investment mistakes to avoid when working with a financial advisor in Singapore. This is the 'Zenith Approach'. It's a commitment to your long-term success over short-term product sales. We prioritize your life goals. Whether you're building a legacy for your children or securing a comfortable retirement, we're here to guide you. Every decision we make together is grounded in your unique vision and risk capacity.
Why a Boutique Perspective Matters
We've moved away from the coldness of traditional banking. We offer personalized wealth analysis that looks at your whole life. This boutique perspective allows us to be proactive and attentive. We support young families and pre-retirees through tailored roadmaps that evolve as you do. Our commitment to professional integrity means transparent communication is our baseline, not an afterthought. You'll always know the 'why' behind every recommendation. We don't just manage assets; we manage relationships. This human-centric approach ensures your financial planner is always aligned with your best interests. It's about clarity, trust, and consistent growth. We want you to feel empowered by your choices, not overwhelmed by them.
Ready to Optimise Your Wealth Strategy?
Your first discovery session is about listening. We want to understand your vision before we look at your numbers. During this session, our financial consultant will audit your current holdings for the strategic errors discussed in this guide. We'll look for hidden gaps in your wealth protection. We'll identify where your diversification might be lacking. We also check if your current strategy actually utilizes the i12 investments framework for maximum efficiency. This audit provides a clear baseline for your future growth. It identifies the common investment mistakes to avoid when working with a financial advisor in Singapore that might be draining your wealth. It's time to stop worrying about your portfolio and start growing it with confidence. Connect with our team to start your journey and see how a focused, professional partnership can transform your financial future. We're ready when you are.
Take Charge of Your Wealth Journey
Avoiding the common investment mistakes to avoid when working with a financial advisor in Singapore starts with a shift in mindset. You've learned that wealth management isn't a "set and forget" task; it's a proactive partnership. By being fully transparent about your assets and committing to the swift implementation of your strategy, you ensure your money actually works for your future. Whether you're refining your retirement roadmap or securing education funding, consistency and clarity are your greatest assets in the 2026 market.
At Zenith Wealth, we don't just offer advice; we provide a boutique, human-centric experience. As authorised representatives of finexis advisory, we specialize in the i12 investments framework to keep your portfolio disciplined and diversified. Don't let your financial plan remain a "paper plan" any longer. It's time to build a relationship that prioritizes your life goals over institutional product numbers.
Book a Discovery Session with a Zenith Financial Consultant to audit your current strategy and start your journey toward lasting peace of mind. We're excited to grow alongside you!
Frequently Asked Questions
What is the difference between a financial consultant and a financial planner in Singapore?
In the local context, these terms are often used interchangeably to describe professionals who provide wealth management and insurance advice. A financial planner often implies a focus on holistic roadmaps, whereas a financial consultant might be viewed as a guide for specific investment management or protection needs. At Zenith Wealth, our professionals act as your Modern Professional Guide, ensuring your strategy aligns with your long-term life goals regardless of the specific title used.
How often should I meet with my financial consultant to review my investments?
You should aim for a formal review at least once a year, or whenever a major life event occurs. Marriage, a career shift, or receiving an inheritance are critical times to pivot your strategy. Regular reviews help you avoid common investment mistakes to avoid when working with a financial advisor in Singapore, such as letting your portfolio drift away from your target asset allocation. These check-ins ensure your wealth protection remains robust as your lifestyle evolves.
Can a financial consultant help me with my CPF and SRS accounts?
Yes, a financial planner can integrate your CPF and SRS accounts into your broader wealth management strategy. These local schemes are vital for tax efficiency and retirement planning in Singapore. We look at your CPF LIFE estimates and SRS tax relief limits to ensure your private investments complement these government accounts. This holistic view prevents over-concentration and ensures every dollar in your portfolio is working toward your bespoke retirement roadmap.
What are the typical fees when working with a financial consultant at Zenith Wealth?
Our fee structure is transparent and depends on the type of service you require. At Zenith Wealth, we offer commission-based intermediation for financial products, where insurance companies or fund houses pay for the placement and ongoing servicing of your portfolio. We also provide fee-based comprehensive financial planning for customized roadmaps and strategic wealth analysis. We discuss all costs upfront during our discovery sessions to ensure you have complete clarity on how we are compensated for our expertise.
Why is i12 investments mentioned as a key framework for growth?
The i12 investments framework is a disciplined methodology we use to remove emotional bias from the investment process. It focuses on long-term structural trends rather than short-term market noise. By using this framework, your financial consultant can help you build a high-performing, diversified portfolio that balances regional stability with global growth. It is a core part of the 'Zenith Approach,' combining technical rigor with a deep understanding of your personal financial milestones.
What happens if my risk appetite changes after I've already started an investment plan?
Your financial planner will help you rebalance your portfolio to match your new risk profile immediately. Risk appetite isn't static; it often shifts as you move from a growth-focused career phase to a wealth-protection phase near retirement. We use the i12 investments framework to adjust your asset allocation without triggering unnecessary tax liabilities or exit fees. This flexibility ensures your investment management strategy always feels comfortable and aligned with your current financial capacity.
Do I need a large sum of money to start working with a financial consultant?
No, you don't need to be a high-net-worth individual to begin planning your future. We work with young working adults and parents who are just starting their wealth-building journey. Whether you're focusing on education funding for your children or starting your first retirement plan, the key is consistency rather than the initial amount. Starting early allows you to leverage compounding growth, which is often more powerful than waiting for a large sum to invest.
How do I know if my current financial consultant is making mistakes with my portfolio?
Lack of transparency and poor communication are major red flags. If you don't understand the 'why' behind your assets or if your portfolio hasn't been reviewed in over a year, you might be facing common investment mistakes to avoid when working with a financial advisor in Singapore. A good consultant should provide regular updates and clear explanations. If your current advice feels like a cold institutional sales pitch, it may be time for a fresh, boutique perspective.


